Businorem ipsum dolor sit amet cons interdum quam duis variuy time honored tradition etting .
Businorem ipsum dolor sit amet cons interdum quam duis variuy time honored tradition etting .
 November 6, 2026
Access to credit can open doors to financial opportunities, but ensuring that borrowers can manage credit responsibly is what makes financial inclusion truly meaningful.
Imagine an individual who has just received approval for their first personal loan. For them, it could mean meeting an important financial requirement, managing an emergency or achieving a long-awaited personal goal. For a small business owner, access to working capital could mean expanding operations, investing in infrastructure or exploring new markets. These possibilities highlight the importance of credit in driving economic participation and financial growth. However, while the approval and disbursement of a loan often mark the successful completion of a lending process, they represent only the beginning of a much larger financial journey for the borrower.
India’s credit ecosystem has evolved considerably over the years. The expansion of digital lending platforms, improved financial infrastructure, wider credit bureau coverage and technology-driven underwriting have made formal credit increasingly accessible to individuals and businesses. Financial institutions are reaching customer segments that were historically underserved, while digital solutions are simplifying the borrowing experience. These developments have strengthened financial inclusion and created opportunities for a larger population to participate in the formal credit ecosystem. Yet, expanding access to credit also brings an equally important responsibility: ensuring that borrowers understand how to manage the financial commitments they undertake.
A successful lending transaction does not necessarily translate into a financially healthy borrowing experience. Once a loan is disbursed, borrowers must navigate repayment schedules, interest obligations, credit utilisation and other financial commitments. For individuals managing multiple loans, even a temporary disruption in income can create repayment difficulties. Similarly, borrowers who are unfamiliar with credit reporting practices may not fully understand how delayed payments, excessive borrowing or inaccurate account information can influence their credit profiles. These challenges highlight an important gap in the lending ecosystem. While significant attention is given to evaluating borrowers before extending credit, the importance of supporting them throughout the repayment journey deserves greater recognition.
This is where the concept of credit health becomes particularly relevant. A credit score is undoubtedly an important indicator of an individual’s creditworthiness, helping lenders assess repayment behaviour and understand potential credit risks. However, credit health extends beyond a three-digit number. It involves understanding the borrower’s overall credit exposure, repayment consistency, utilisation of available credit and the accuracy of information reflected in their credit report. A borrower may have a reasonable credit score but still face challenges arising from multiple financial obligations or inaccurate account information. Therefore, evaluating credit health requires a broader understanding of an individual’s financial behaviour rather than relying exclusively on a numerical indicator.
Credit information plays a fundamental role in this process. Credit information companies collect and maintain data submitted by participating lending institutions, creating a record of an individual’s borrowing and repayment history. This information helps lenders make informed credit decisions and enables borrowers to understand how their financial behaviour is represented within the formal credit ecosystem. However, the usefulness of this information depends heavily on its accuracy, completeness and timely reporting. An incorrect outstanding balance, an outdated account status or an inaccurately reported repayment history can create a misleading representation of a borrower’s financial position. Regularly reviewing credit reports and addressing discrepancies through the appropriate channels can therefore become an important part of responsible financial management.
Another important aspect of credit health is the relationship between responsible lending and responsible borrowing. Financial institutions must evaluate repayment capacity, communicate loan terms transparently and follow appropriate lending practices. At the same time, borrowers must understand their financial obligations, assess their ability to repay and make informed borrowing decisions. These responsibilities are interconnected. Extending credit without adequate consideration of repayment capacity can expose borrowers to financial stress, while borrowing without understanding the associated obligations can create difficulties over time. A sustainable credit ecosystem requires both lenders and borrowers to approach credit with greater awareness and accountability.
Technology presents an opportunity to bridge the gap between credit access and credit health. The same technological developments that have made loan applications and approvals faster can also be used to improve post-disbursement credit management. Digital platforms can help borrowers understand their credit reports, monitor account information, track repayment obligations and identify potential discrepancies. Similarly, lenders can leverage technology to strengthen customer engagement, improve credit information management and support more effective monitoring throughout the loan lifecycle. The objective should not simply be to make borrowing faster and more convenient, but also to make credit management more transparent, accessible and understandable.
This shift also creates opportunities for organisations operating within the credit information and credit counselling ecosystem. Beyond facilitating access to credit, there is a growing need for solutions that help borrowers understand their credit profiles and take informed steps towards maintaining or improving their credit standing. Simplifying complex credit information, creating awareness about repayment behaviour and providing guidance on addressing reporting discrepancies can contribute towards a more informed borrowing community. Such initiatives can complement the efforts of financial institutions and support the broader objective of building a financially aware population.
As India’s lending ecosystem continues to expand, the definition of financial inclusion must evolve alongside it. The number of loans disbursed and the volume of credit extended remain important indicators of growth, but they do not independently reflect the long-term financial well-being of borrowers. A stronger credit ecosystem must also focus on repayment sustainability, information accuracy, financial awareness and the ability of individuals and businesses to manage their credit obligations effectively. The future of lending will therefore depend not only on how efficiently institutions can extend credit, but also on how effectively the ecosystem supports borrowers after credit has been made available.
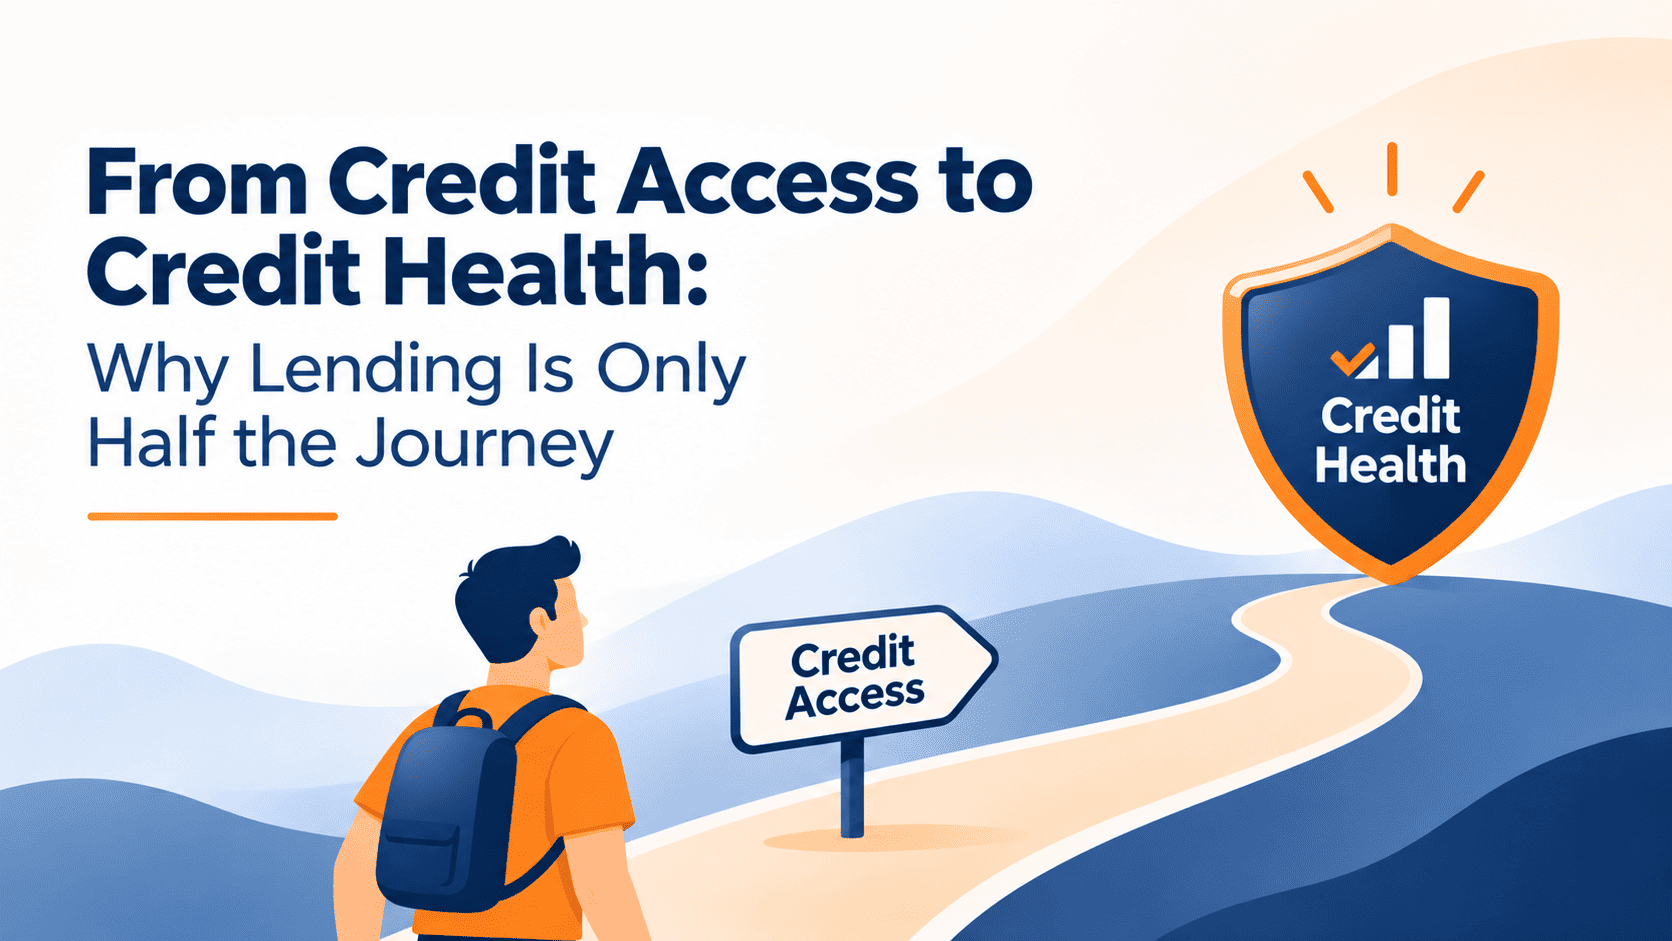
Credit access opens the door to financial opportunities, but credit awareness and responsible management help borrowers make the most of those opportunities. Lending may complete a transaction, but maintaining credit health is an ongoing journey. Ultimately, the true success of financial inclusion should not be measured only by how many people gain access to credit, but by how confidently, responsibly and sustainably they can participate in the credit ecosystem.