Businorem ipsum dolor sit amet cons interdum quam duis variuy time honored tradition etting .
Businorem ipsum dolor sit amet cons interdum quam duis variuy time honored tradition etting .
 October 23, 2026
It is a fair question, and one many cardholders eventually ask. A bank raises a credit limit from fifty thousand rupees to one-and-a-half lakh, and the advice that follows is to still keep usage below thirty percent of it. If a higher limit only invites a proportionally higher restriction, it can seem like the increase changes nothing at all. The confusion, however, comes from treating the limit as something meant to be used, when its real value lies almost entirely in what it does to the ratio underneath.
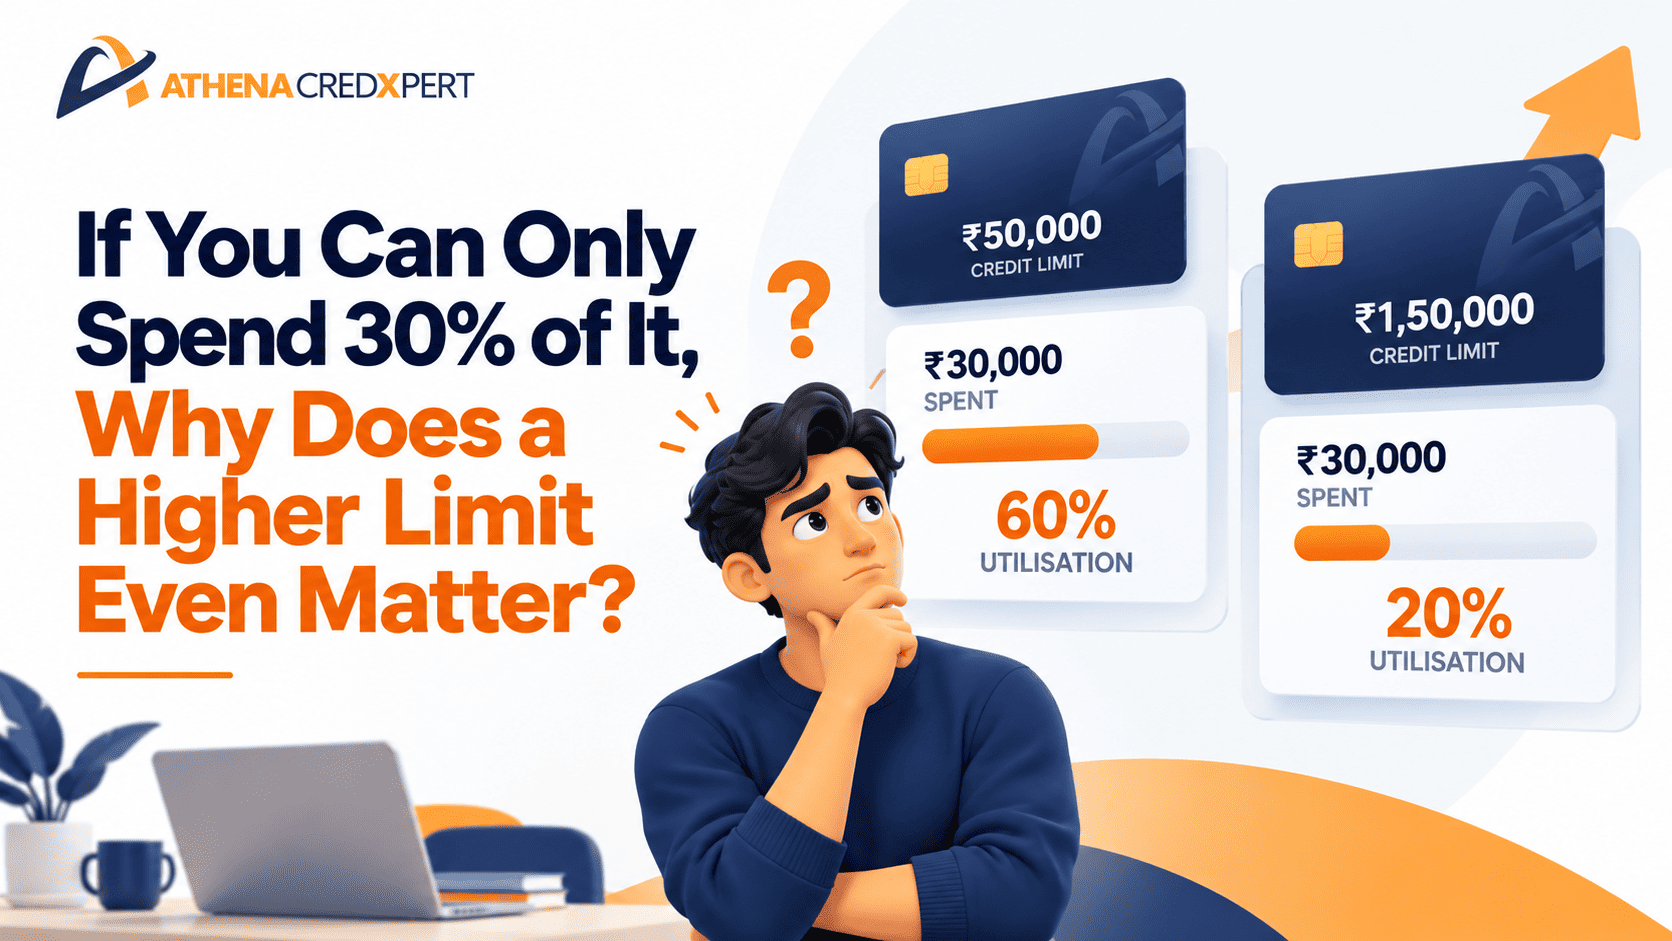
Credit utilisation is the percentage of available credit currently in use, calculated by dividing the outstanding balance by the total limit. Consider two borrowers, both spending thirty thousand rupees in a month. One holds a card with a fifty-thousand-rupee limit and ends up at sixty percent utilisation. The other holds a card with a one-and-a-half-lakh-rupee limit and sits at twenty percent. Neither has changed a single spending habit, and neither has missed a payment, yet one appears, to a lender or bureau, to be leaning heavily on their available credit, while the other does not. This is the entire mechanism at work: the limit is not the ceiling one is expected to spend up to; it is the denominator against which existing spending is measured.
Source: Hero FinCorp — Credit Utilisation Ratio: Meaning, Calculation & How To Improve
This is precisely why a higher limit, used with the same spending pattern as before, tends to improve rather than restrict a credit profile. Credit utilisation is widely regarded as the second most influential factor in a credit score after payment history itself, which means a lower ratio at identical spending levels can measurably strengthen the score over time, even without any change in financial behaviour.
Source: Hero FinCorp — Credit Utilisation Ratio: Meaning, Calculation & How To Improve
A higher limit does something else that is easy to overlook: it creates room for irregular months without immediately pushing utilisation into territory that concerns a lender. A large one-time expense, a medical bill, a festival season, a set of purchases clustered before a statement date, can be absorbed within a higher limit at a ratio that still looks reasonable, whereas the same expense against a lower limit might spike utilisation sharply for that billing cycle. Since card issuers report the balance as it stands on the statement generation date rather than the due date, a large purchase made just before that date can register as high utilisation for the month even if it is repaid in full before the payment deadline. A higher limit provides a buffer against exactly this kind of timing mismatch, without requiring the cardholder to actually change what or when they spend.
Source: Hero FinCorp — Credit Utilisation Ratio: Meaning, Calculation & How To Improve
There is also a structural reason a higher limit is worth holding onto rather than viewing as excess capacity to be trimmed. Closing an unused card, or a lender reducing a sanctioned limit, removes that portion of available credit from the total, which can push the utilisation ratio up sharply even if outstanding balances remain unchanged. A person carrying the same spending across three cards, one of which is then closed, can see overall utilisation rise significantly simply because the denominator shrank, not because they borrowed any more than before. Idle, unused limit is not wasted capacity in the way it might appear; it is what keeps the ratio favourable when it is needed most.
Source: NerdWallet — How to Calculate Your Credit Utilization Ratio; Kotak Mahindra Bank — Credit Card Utilization Ratio
None of this means the thirty percent figure should be treated as a rigid ceiling never to be crossed. It is a guideline reflecting what most lenders consider indicative of responsible credit use, not a threshold that causes automatic harm the moment it is exceeded. An occasional month above it, quickly brought back down through repayment, does not undo an otherwise sound credit history. What matters more than the exact percentage is the pattern behind it, whether usage is consistently high across cycles or an isolated event followed by prompt repayment, and whether that usage is spread sensibly across available cards rather than concentrated heavily on one.
Source: Bajaj Housing Finance — Credit Card Utilization Ratio; Federal Bank — How Credit Utilization Ratio Affects Your Credit Score
Seen this way, a high credit limit is not an invitation to spend more; it is protection against how the same spending gets read by the institutions deciding what one qualifies for next. The value of a higher limit was never in using more of it. It was always in needing less of it to say the same thing about how the money is being handled.