Businorem ipsum dolor sit amet cons interdum quam duis variuy time honored tradition etting .
Businorem ipsum dolor sit amet cons interdum quam duis variuy time honored tradition etting .
 November 20, 2026
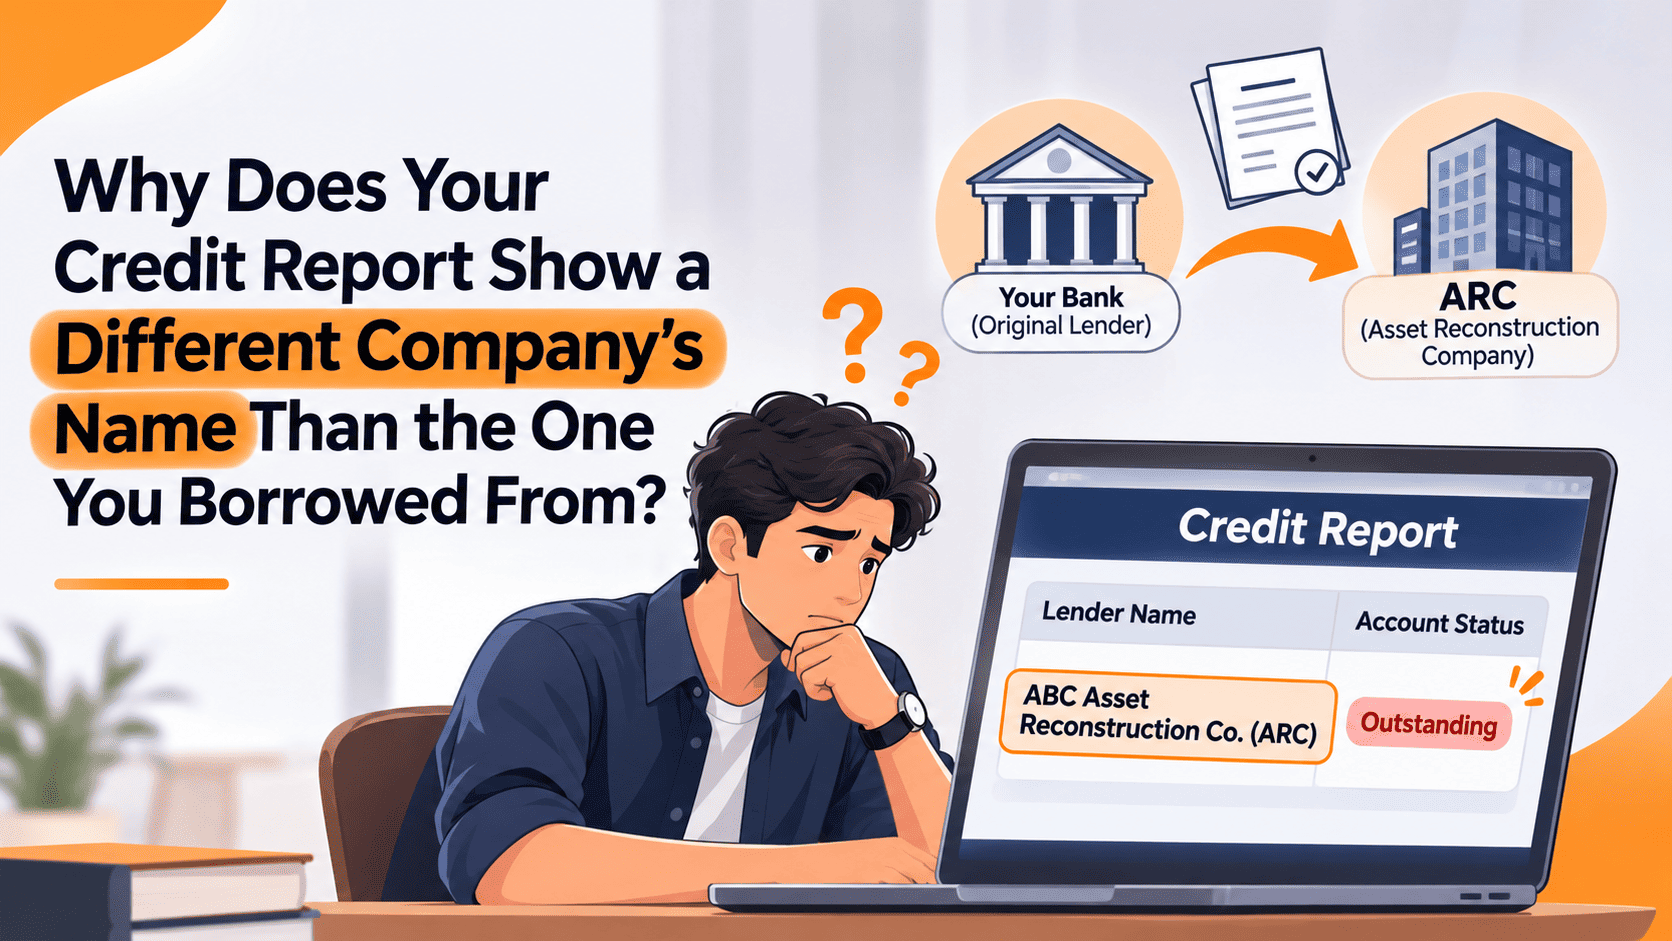
Imagine you have missed several loan payments and your bank informs you that your loan has been transferred to an Asset Reconstruction Company (ARC). You may wonder: Who is this company? Do you still owe the money? Why is its name appearing in your Credit Report?
These are important questions, especially when you are already dealing with repayment difficulties. When a loan remains unpaid for a long time, the original lender may sell it to an ARC to recover the outstanding amount.
Let us understand what this means for you and what you should keep in mind.
What Is an Asset Reconstruction Company (ARC)?
An Asset Reconstruction Company (ARC) is a company registered with the Reserve Bank of India (RBI). It buys loans that banks and other financial institutions are finding difficult to recover.
For example, if you have taken a personal loan or a home loan and have not made repayments for a prolonged period, your bank may classify the loan as a Non-Performing Asset (NPA). In simple terms, this means the loan has remained overdue beyond the period prescribed by RBI.
The bank may then decide to sell the loan to an ARC. The ARC takes over the rights relating to that loan and becomes responsible for managing its recovery.
The sale of your loan does not automatically waive your outstanding dues. You are still required to address the repayment obligation, although the institution managing the loan may have changed.
Why Has Your Loan Been Transferred to an ARC?
Banks may sell loans to ARCs when borrowers have not been making repayments and the accounts have become stressed. This allows banks to reduce their exposure to loans that are difficult to recover and focus on their regular lending activities. For a borrower, this means that the company contacting them about the outstanding loan may no longer be the original bank or financial institution.
What Happens After Your Loan Is Sold to an ARC?
Once an ARC acquires your loan, it takes over the rights of the original lender in relation to that loan. It may contact you to discuss repayment or explore ways to recover the outstanding amount.
Depending on your loan type, the ARC may consider different approaches:
Why Is an ARC’s Name Appearing in Your Credit Report?
When a bank sells your loan to an ARC, the ARC is required to report information about the acquired loan to Credit Information Companies (Credit Bureaus). Under RBI’s 2025 directions, ARCs must report borrower information to all four Credit Bureaus in the prescribed format.
As a result, you may see the ARC’s name against your existing loan account in your Credit Report. This does not mean you have taken a new loan.
Here is what you should know:
What Happens to Your Credit Report If You Settle the Loan?
If an ARC agrees to a settlement and you complete the agreed payment, your Credit Report should be updated accordingly. However, there is an important difference between full repayment and settlement.
A settled account may be viewed differently by future lenders because the original dues were not repaid in full. It does not automatically restore your credit history or guarantee approval of future loans.
Before making a settlement payment, obtain the terms in writing. After payment, retain the settlement letter and receipts, and check whether your Credit Report reflects the correct status.
What Should You Do If an ARC Appears in Your Credit Report?
If you notice an ARC’s name against your loan account, take the following steps:
Remember, the ARC’s name appearing in your Credit Report does not necessarily indicate an error. Always verify the reported information against your loan documents and payment records.