Businorem ipsum dolor sit amet cons interdum quam duis variuy time honored tradition etting .

Sydney Harbour Circular City of Sydney,Australia.

From Credit Access to Credit Health: Why Lending Is Only Half the Journey

Access to credit can open doors to financial opportunities, but ensuring that borrowers can manage credit responsibly is what makes financial inclusion truly meaningful.  Imagine an individual who has just received approval for their first personal loan. For them, it could mean meeting an important financial requirement, managing an emergency or achieving a long-awaited personal […]
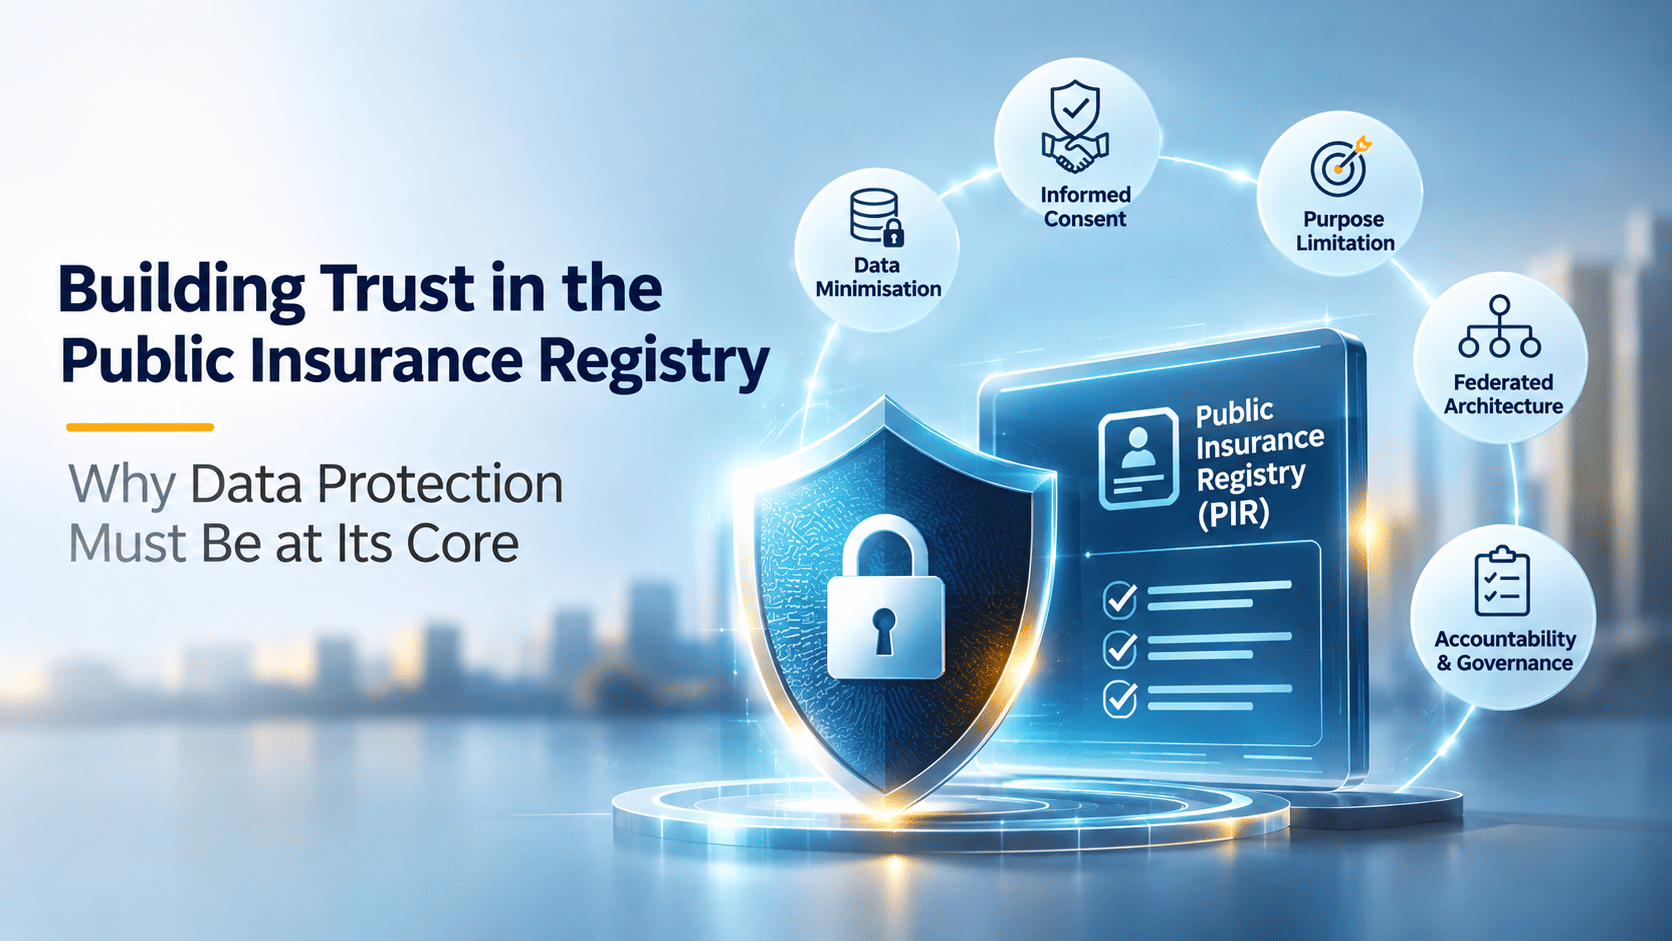
Building Trust in the Public Insurance Registry: Why Data Protection Must Be at Its Core

As IRDAI explores a shared digital infrastructure for insurance, the real test will be balancing data accessibility with privacy, consent and accountability.  India’s proposed Public Insurance Registry (PIR) could address a longstanding challenge in the insurance ecosystem: fragmented information across insurers, intermediaries and other institutions. By enabling standardised and interoperable access to insurance information, the […]

Prepaying a Loan Early: When It Actually Saves Money, and When It Doesn’t

Coming into some extra money, a bonus, a maturing fixed deposit, an inheritance, tends to raise the same question for anyone carrying a loan: should this go toward closing the debt sooner. The instinct to say yes is understandable, and often correct, but not automatically so. Whether prepayment genuinely saves money depends on a set […]

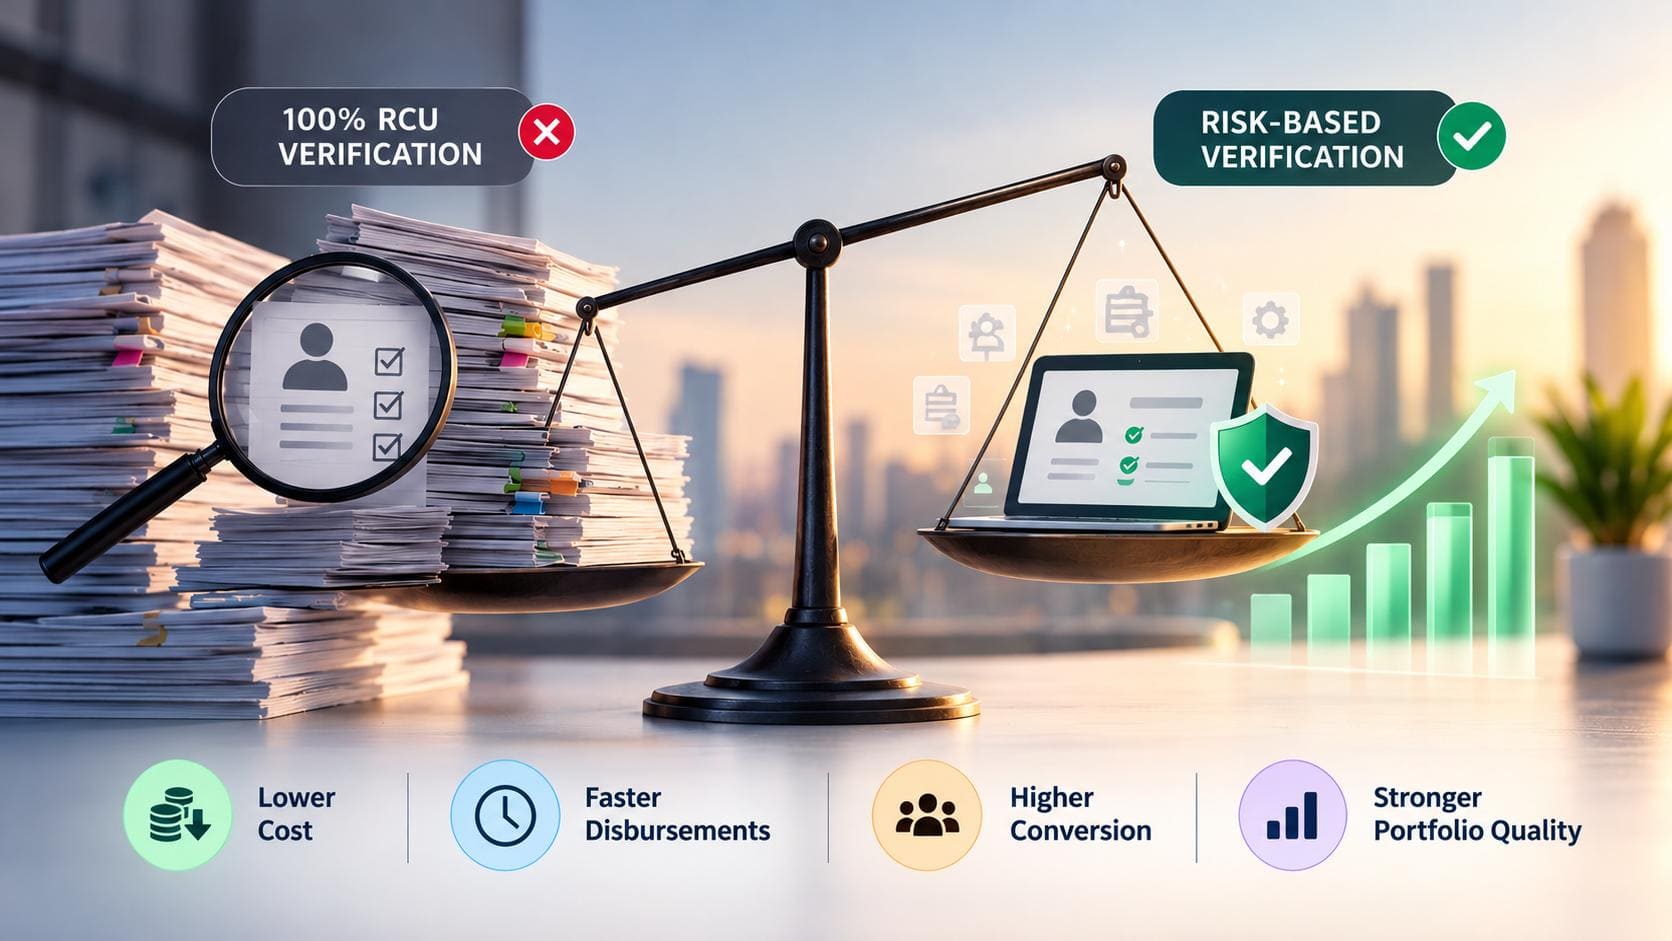
Rethinking 100% RCU Verification: Balancing Risk Containment with Lending Growth

In an increasingly competitive lending landscape, lenders are under pressure to scale disbursements, improve customer experience and maintain portfolio quality, while managing cost of operations. Against this backdrop, 100% Risk Containment Unit (RCU) verification warrants a closer look. While universal verification strengthens the coverage of pre-disbursement controls, applying the same verification intensity across the loan […]

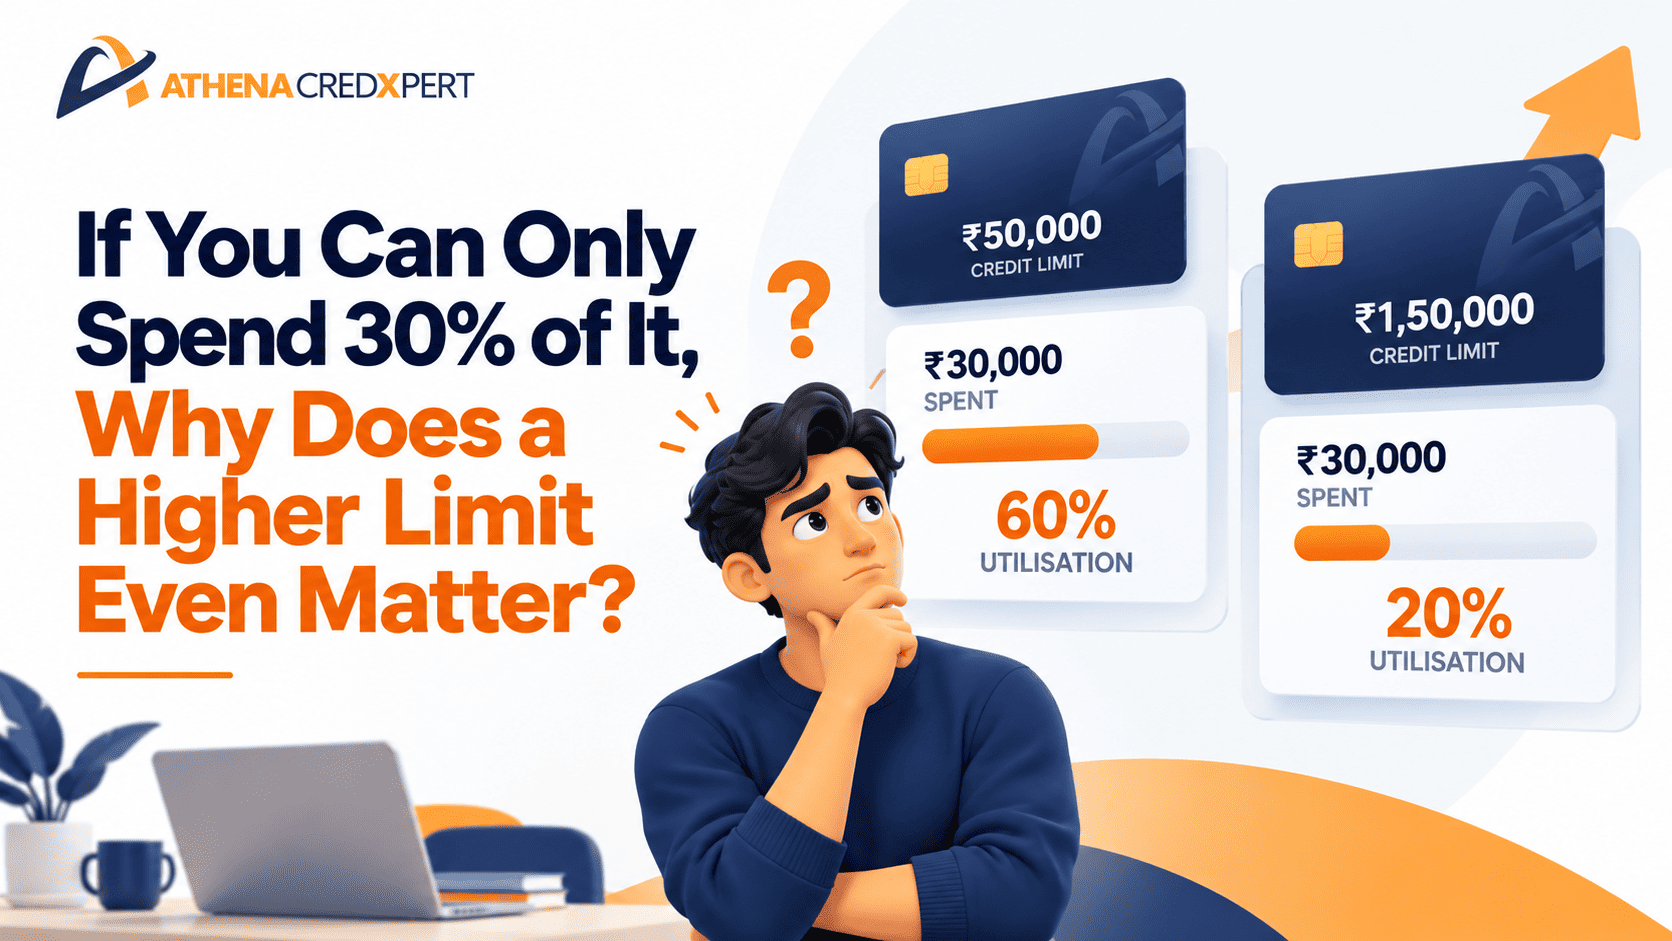
If You Can Only Spend 30% of It, Why Does a Higher Limit Even Matter?

It is a fair question, and one many cardholders eventually ask. A bank raises a credit limit from fifty thousand rupees to one-and-a-half lakh, and the advice that follows is to still keep usage below thirty percent of it. If a higher limit only invites a proportionally higher restriction, it can seem like the increase […]